
First-Time Homebuyer Costs 2026: Buying a first home in the United States has become increasingly difficult as elevated property prices, mortgage interest rates, and additional ownership expenses put pressure on household budgets.
Even as more affordable properties become available in some markets, many Americans continue to struggle with the financial requirements of homeownership.
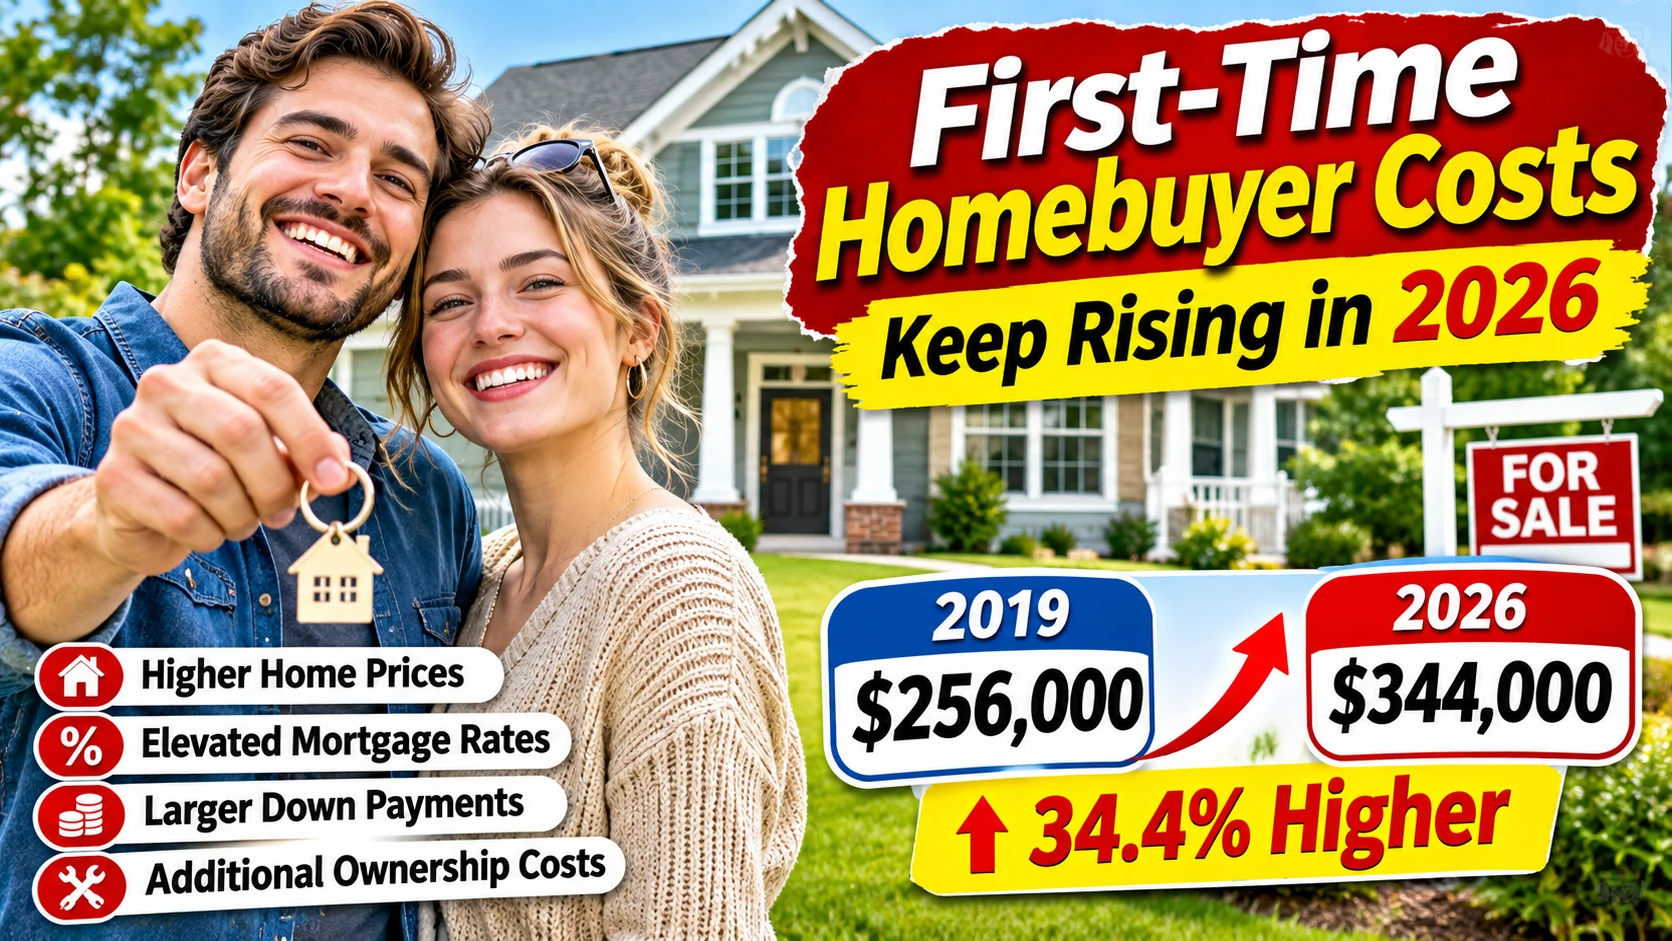
A 2026 Realtor.com analysis found that the average starter home costs approximately $344,000, compared with $256,000 in 2019.
Meanwhile, the estimated minimum annual income needed to afford an entry-level property has climbed from approximately $43,000 to $78,000.
These figures reveal why many prospective buyers are delaying one of life’s biggest financial decisions.
🏠 How Much Does a Starter Home Cost in 2026?
According to Realtor.com’s analysis of Census data, the average US starter home costs approximately $344,000 in 2026.
The analysis defines starter homes as properties priced below $350,000 or below 80% of the median home price in a metropolitan area.
In 2019, the comparable average was approximately $256,000.
That represents an increase of $88,000, or roughly 34.4%, over seven years.
For prospective homeowners, the higher purchase price creates several financial challenges.
A more expensive property generally requires a larger down payment, increases the amount borrowed, and can lead to higher property taxes and insurance expenses.
Buyers who were previously able to afford a modest home may now need additional savings or a higher household income.
🏡 First-Time Homebuyer Costs: 2019 vs 2026
US starter-home affordability comparison based on reported Realtor.com research.
Annual Income Needed
Illustrative Monthly Mortgage Payments
Example: $344,000 home, 10% down, $309,600 loan, 30-year fixed mortgage. Principal and interest only.
Source: Realtor.com analysis of Census data, reported by Yahoo Finance in July 2026. Mortgage payments are illustrative calculations, not current lender quotes. Taxes, insurance, PMI, HOA fees and maintenance are excluded.
💰 First-Time Homebuyer Income Requirements Have Increased
One of the biggest challenges is the widening gap between housing costs and household earnings.
Realtor.com’s analysis estimates that the minimum annual income needed to afford a typical starter home increased from approximately $43,000 in 2019 to $78,000 in 2026.
That represents an increase of about 81.4%.
The required income has therefore grown considerably faster than the starter-home price itself.
Higher mortgage rates help explain this difference.
When borrowing costs rise, buyers must devote more of their monthly income to interest payments, even if the property’s price remains unchanged.
This makes mortgage qualification more difficult, particularly for younger households that have not yet accumulated substantial savings.
📊 US Starter Home Affordability: 2019 vs. 2026
| Housing affordability measure | 2019 | 2026 |
|---|---|---|
| Average starter-home price | $256,000 | $344,000 |
| Estimated minimum annual income | $43,000 | $78,000 |
| Home-price increase | — | 34.4% |
| Income-requirement increase | — | 81.4% |
The comparison highlights an important distinction.
Although starter-home prices have risen substantially, the income needed to qualify for homeownership has increased even more sharply.
That combination has made entry-level housing less accessible for many Americans.
📈 Mortgage Rates Are Adding Pressure to Homebuyers
Mortgage interest rates are another major reason homeownership has become more expensive.
During November 2026, US mortgage rates remained elevated.
Freddie Mac reported an average 30-year fixed mortgage rate of approximately 7.11% for the week ending November 12.
Meanwhile, daily mortgage-rate indicators moved higher following stronger-than-expected inflation data.
Even small changes in borrowing costs can significantly affect monthly payments.
For example, consider a buyer purchasing a $344,000 home with a 10% down payment.
The mortgage principal would be $309,600.
On a 30-year fixed mortgage, the estimated monthly principal-and-interest payment would be:
- At 6% interest: approximately $1,856.
- At 7% interest: approximately $2,060.
- At 8% interest: approximately $2,272.
These are illustrative calculations, not mortgage offers.
They exclude property taxes, homeowners insurance, mortgage insurance, maintenance, and other expenses.
The difference between a 6% and 8% mortgage rate would be approximately $416 per month on the same loan.
Over time, that difference can have a substantial impact on household finances.
😮 Hidden Costs Make Buying a First Home Even Harder
Many first-time buyers focus on saving for a down payment.
However, purchasing a home involves several additional expenses.
1. Closing Costs
Buyers may need to pay lender fees, title-related expenses, appraisal charges, legal costs, and other transaction fees.
These costs vary depending on the location, loan program, lender, and property.
2. Property Taxes
Property taxes are determined by state and local authorities.
A buyer should review the property’s current assessment and consider whether taxes could change after the purchase.
3. Homeowners Insurance
Homeowners insurance is another important recurring expense.
Premiums depend on factors such as property value, location, construction characteristics, and exposure to natural disasters.
4. Private Mortgage Insurance
Many conventional mortgage borrowers who put down less than 20% must pay private mortgage insurance.
This adds to monthly housing expenses until the applicable cancellation requirements are satisfied.
5. Maintenance and Repairs
Homeowners are responsible for repairs, equipment replacement, and general property maintenance.
Expenses such as roofing, plumbing, heating, and air-conditioning repairs can create unexpected financial pressure.
For this reason, buyers should evaluate the full cost of ownership rather than relying only on the advertised property price.
🌎 Housing Affordability Varies Across the United States
The national housing market does not tell the entire story.
Starter-home prices vary significantly by region.
In parts of the South and West, increased construction activity has helped improve housing availability.
Some markets have experienced modest price declines from their 2022 peaks.
However, conditions remain more challenging in regions where residential construction has been limited.
The Northeast is particularly expensive.
According to the Realtor.com analysis, a typical starter home in the Northeast costs approximately $444,000.
That is around $100,000 more than the national starter-home average.
These differences demonstrate why first-time buyers should research local market conditions rather than relying exclusively on national statistics.
🏘️ More Starter Homes Are Available, but Affordability Remains Difficult
There is some encouraging news for prospective buyers.
The number of homes priced below $350,000 has improved compared with 2022.
Realtor.com’s analysis found approximately 220,000 more homes in this price category than four years earlier.
However, the supply remained approximately 300,000 homes below pre-pandemic levels.
Greater inventory can provide buyers with more choices and potentially stronger negotiating opportunities.
But increased availability does not automatically make properties affordable.
High monthly mortgage payments can still prevent buyers from qualifying for financing.
The report also found that sales of homes priced below $350,000 declined approximately 10% year over year in April 2026.
This suggests that financial constraints remain significant even when more homes enter the market.
💡 How First-Time Homebuyers Can Prepare Financially
Prospective buyers can take several steps to improve their financial readiness.
Build a realistic budget: Calculate mortgage payments alongside taxes, insurance, utilities, maintenance, and possible homeowners association fees.
Improve creditworthiness: A stronger credit profile may help buyers qualify for more favorable mortgage terms.
Compare mortgage lenders: Interest rates, fees, and loan conditions can differ between lenders.
Save beyond the down payment: Maintain funds for closing costs, moving expenses, repairs, and emergencies.
Explore assistance programs: Eligible buyers may qualify for state or local down-payment assistance and other first-time homebuyer initiatives.
Avoid borrowing the maximum available amount: Mortgage preapproval does not necessarily mean that the approved payment fits comfortably within a household budget.
A careful financial plan can reduce the risk of unexpected expenses after purchasing a property.
❓ Frequently Asked Questions About First-Time Homebuyer Costs
1. What is the average starter-home price in the US in 2026?
A Realtor.com analysis estimates that the average starter home costs approximately $344,000 in 2026, compared with $256,000 in 2019.
2. How much income is needed to buy a starter home?
The same analysis estimates a minimum annual income requirement of approximately $78,000 for a typical entry-level home. Actual requirements depend on location, debts, down payment, mortgage rate, and lender criteria.
3. Why are first-time homebuyer costs increasing?
The main factors include higher home prices, elevated mortgage rates, insurance expenses, property taxes, and other ownership costs.
4. Is a 20% down payment required to buy a first home?
No. Several mortgage programs permit smaller down payments for eligible borrowers. However, lower down payments may increase monthly costs and require mortgage insurance.
5. Will US home prices become more affordable?
Affordability could improve if mortgage rates decline, housing supply increases, or home prices moderate. However, future market conditions are uncertain and differ by region.
✅ Conclusion: Is Buying a First Home Still Possible in 2026?
The US housing market continues to present serious challenges for first-time buyers.
With average starter-home prices around $344,000 and estimated income requirements reaching $78,000, homeownership has become a more demanding financial commitment.
Higher mortgage rates and additional ownership expenses have further increased the pressure.
Although starter-home inventory has improved in some areas, many households remain priced out of their preferred markets.
For prospective buyers, the most important step is understanding the complete financial commitment before purchasing a property.
Careful budgeting, mortgage comparison, realistic expectations, and adequate emergency savings can help buyers make more informed decisions.
The central question for 2026 is not simply whether a household can qualify for a mortgage, but whether it can comfortably afford the long-term cost of owning a home.
Editor’s note: Housing-market statistics reflect published 2026 analyses. Mortgage-payment examples are illustrative calculations and do not include taxes, insurance, or other ownership expenses.